

MD&A · 2025
In this section4 topics
Overview of Operations
Section Introduction
In 2025, Osotspa Public Company Limited (“the Company”) expanded its business across multiple dimensions, encompassing growth in international markets, entry into new product categories within high-potential segments, and operational restructuring initiatives across various areas. These efforts were undertaken to enhance efficiency and further strengthen the Company’s overall capabilities and competitiveness.
Overview of Operations
Market and Competitive Landscape in 2025
In 2025, the energy drink market experienced a slight contraction of 0.1%. Despite this, Osotspa Public Company Limited maintained its leadership position with an average full-year market share of 44.2%. This performance was driven by comprehensive product development addressing all target segments, consistent marketing and brand communication campaigns reinforcing its position as Thailand’s leading brand, and continuous refinement of its route-to-market strategy to expand nationwide distribution coverage, particularly in the convenience store channel, which continued to demonstrate strong growth.
The functional drinks market also declined marginally by 0.1%. Osotspa retained its number one position with an average market share of 46.4%, supported by its flagship brand, Peptine, which gained share amid sustained growth in consumer demand for health-oriented products. The “Brain Fast Charge” campaign further strengthened brand recognition and delivered double-digit sales growth. In addition, C-Vitt maintained a dominant position in the vitamin C drink segment, achieving a market share of 76.6%, reflecting the continued strength of the brand.
Meanwhile, the personal care market, including liquid baby soap, baby powder, and deodorant products, contracted by approximately 4–7% and the contraction was seen in distribution channels. The decline was primarily attributable to subdued consumer purchasing power and intensified competition in the FMCG sector. Nevertheless, the Company retained its leading market share in the liquid baby soap segment and increased its share in baby powder and both female and male deodorant categories, supported by more intensive and targeted marketing communications.
Operational Overview 2025
At the beginning of 2025, Osotspa Public Company Limited restructured the sales and distribution model for its energy drink portfolio to enhance the stability and systematic measurement of marketing effectiveness, supporting long-term growth. As a result, domestic beverage revenue declined by 14.6% year-on-year in the first half of the year. However, revenue in the second half rebounded, growing 2.8% year-on-year. Overall, domestic beverage revenue for 2025 decreased by 6.4% compared to the previous year. In contrast, international beverage revenue increased by 4.8% year-on-year, driven primarily by significant sales growth in Myanmar and Laos, reflecting the strength of the Company’s beverage brands in these markets. This growth helped offset slower sales in Indonesia and Cambodia from mid-2025 onward, which were impacted by macroeconomic factors. The Company continued to prioritize production and operational efficiency improvements, alongside stringent cost control measures under its “Operational Excellence” strategy. As a result, gross profit margins improved across all product categories. In addition, refinements to the route-to-market strategy, combined with targeted and ROI-driven marketing and trade promotion activities, led to a 7.2% year-on-year reduction in selling and administrative expenses.
As a result of these strategic initiatives, Osotspa reported net profit attributable to the Company of 3,667 million baht in 2025, representing a 123.8% increase from the previous year. Excluding a gain of 295 million baht from the divestment of its investment in the glass bottle manufacturing and distribution business in Myanmar (MGE Group) in the first quarter, and net expenses of 130 million baht incurred in the fourth quarter related to consolidation of production facilities aimed at enhancing future operational efficiency, normalized net profit amounted to 3,503 million baht, an increase of 15.3% year-on-year.
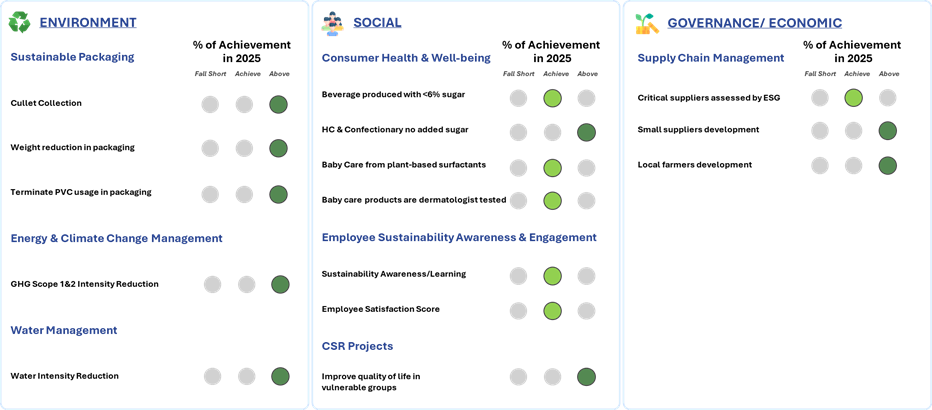
In terms of sustainability, Osotspa remains committed to advancing sustainable business practices. In 2025, the Company achieved its sustainability targets across all three ESG dimensions, Environmental, Social, and Governance, and continues to pursue its long-term commitment to achieving carbon neutrality by 2050.
Beverage Segment
In 2025, revenue from beverage products totaled 21,423 million Baht, representing a decline of 3.3% year-on-year. The decrease was primarily attributable to slower domestic beverage sales following the restructuring of the sales and distribution model in early 2025, which aimed to enhance the stability and systematic measurement of marketing effectiveness. However, domestic beverage sales in the second half of the year recorded growth, partially offsetting the revenue decline in the first half. Meanwhile, international beverage revenue increased by 4.8%, driven mainly by strong sales growth in Myanmar and Laos.
Personal Care Segment
Revenue from personal care products in 2025 amounted to 2,809 million Baht, reflecting a slight increase of 0.2% year-on-year. The growth was primarily driven by increased sales in the adult segment under the Ultra Mild brand, which leverages the brand equity of Babi Mild in gentleness and skin care expertise. The adult segment represents a high-potential market characterized by relatively moderate competition and above-average profit margins.
Other Segments
In 2025, the Company recorded other income of 1,329 million Baht, a decrease of 37.1% from the previous year. The decline was mainly due to lower OEM revenue from the glass bottle product group, reflecting the Company’s strategic focus on its core business and the optimization of glass bottle production capacity to primarily support the Company’s own product portfolio.
Gross Profit Margin
The gross profit margin for 2025 improved to 40.1%, an increase of 2.8 percentage points from the previous year. This expansion was driven by visionary management of raw material and energy cost, continued improvements in production efficiency following capacity optimization, and a higher proportion of international revenue, which carries above-average gross margins.
Selling and Administrative Expenses to Revenue from Sales
The ratio of selling and administrative expenses to revenue from sales in 2025 was 25.2%, decreasing by 0.5 percentage points from the previous year. This reflects enhancements to the route-to-market strategy, the implementation of targeted and ROI-driven marketing and trade promotion activities, and continuous improvements in operational and management efficiency.
Share of Profit from Associates and Joint Ventures
In 2025, the Company recognized a share of profit from associates and joint ventures of 146 million Baht, a decrease of 29.9% year-on-year. The decline was primarily attributable to adjustments in the profit-sharing structure of its joint venture under Osotspa Taisho Co., Ltd., to better align with evolving business conditions and support long-term sustainability.
Net Profit
The Company reported net profit of 3,667 million Baht in 2025, representing an increase of 123.8% from the previous year, driven by improved gross profit margins and reduced selling and administrative expenses. During the year, the Company recognized a gain of 295 million Baht from the divestment of its investment in the glass bottle manufacturing and distribution business in Myanmar (MGE Group) as part of its business restructuring. The Company also recorded net expenses of 130 million Baht related to production consolidation initiatives aimed at enhancing operational efficiency.
In comparison, in 2024 the Company recognized a total net loss of 1,400 million Baht, primarily resulting from business restructuring through the divestment of investments in non-core businesses.
Operating Results & Financial Condition
Introduction
Statement of Financial Position
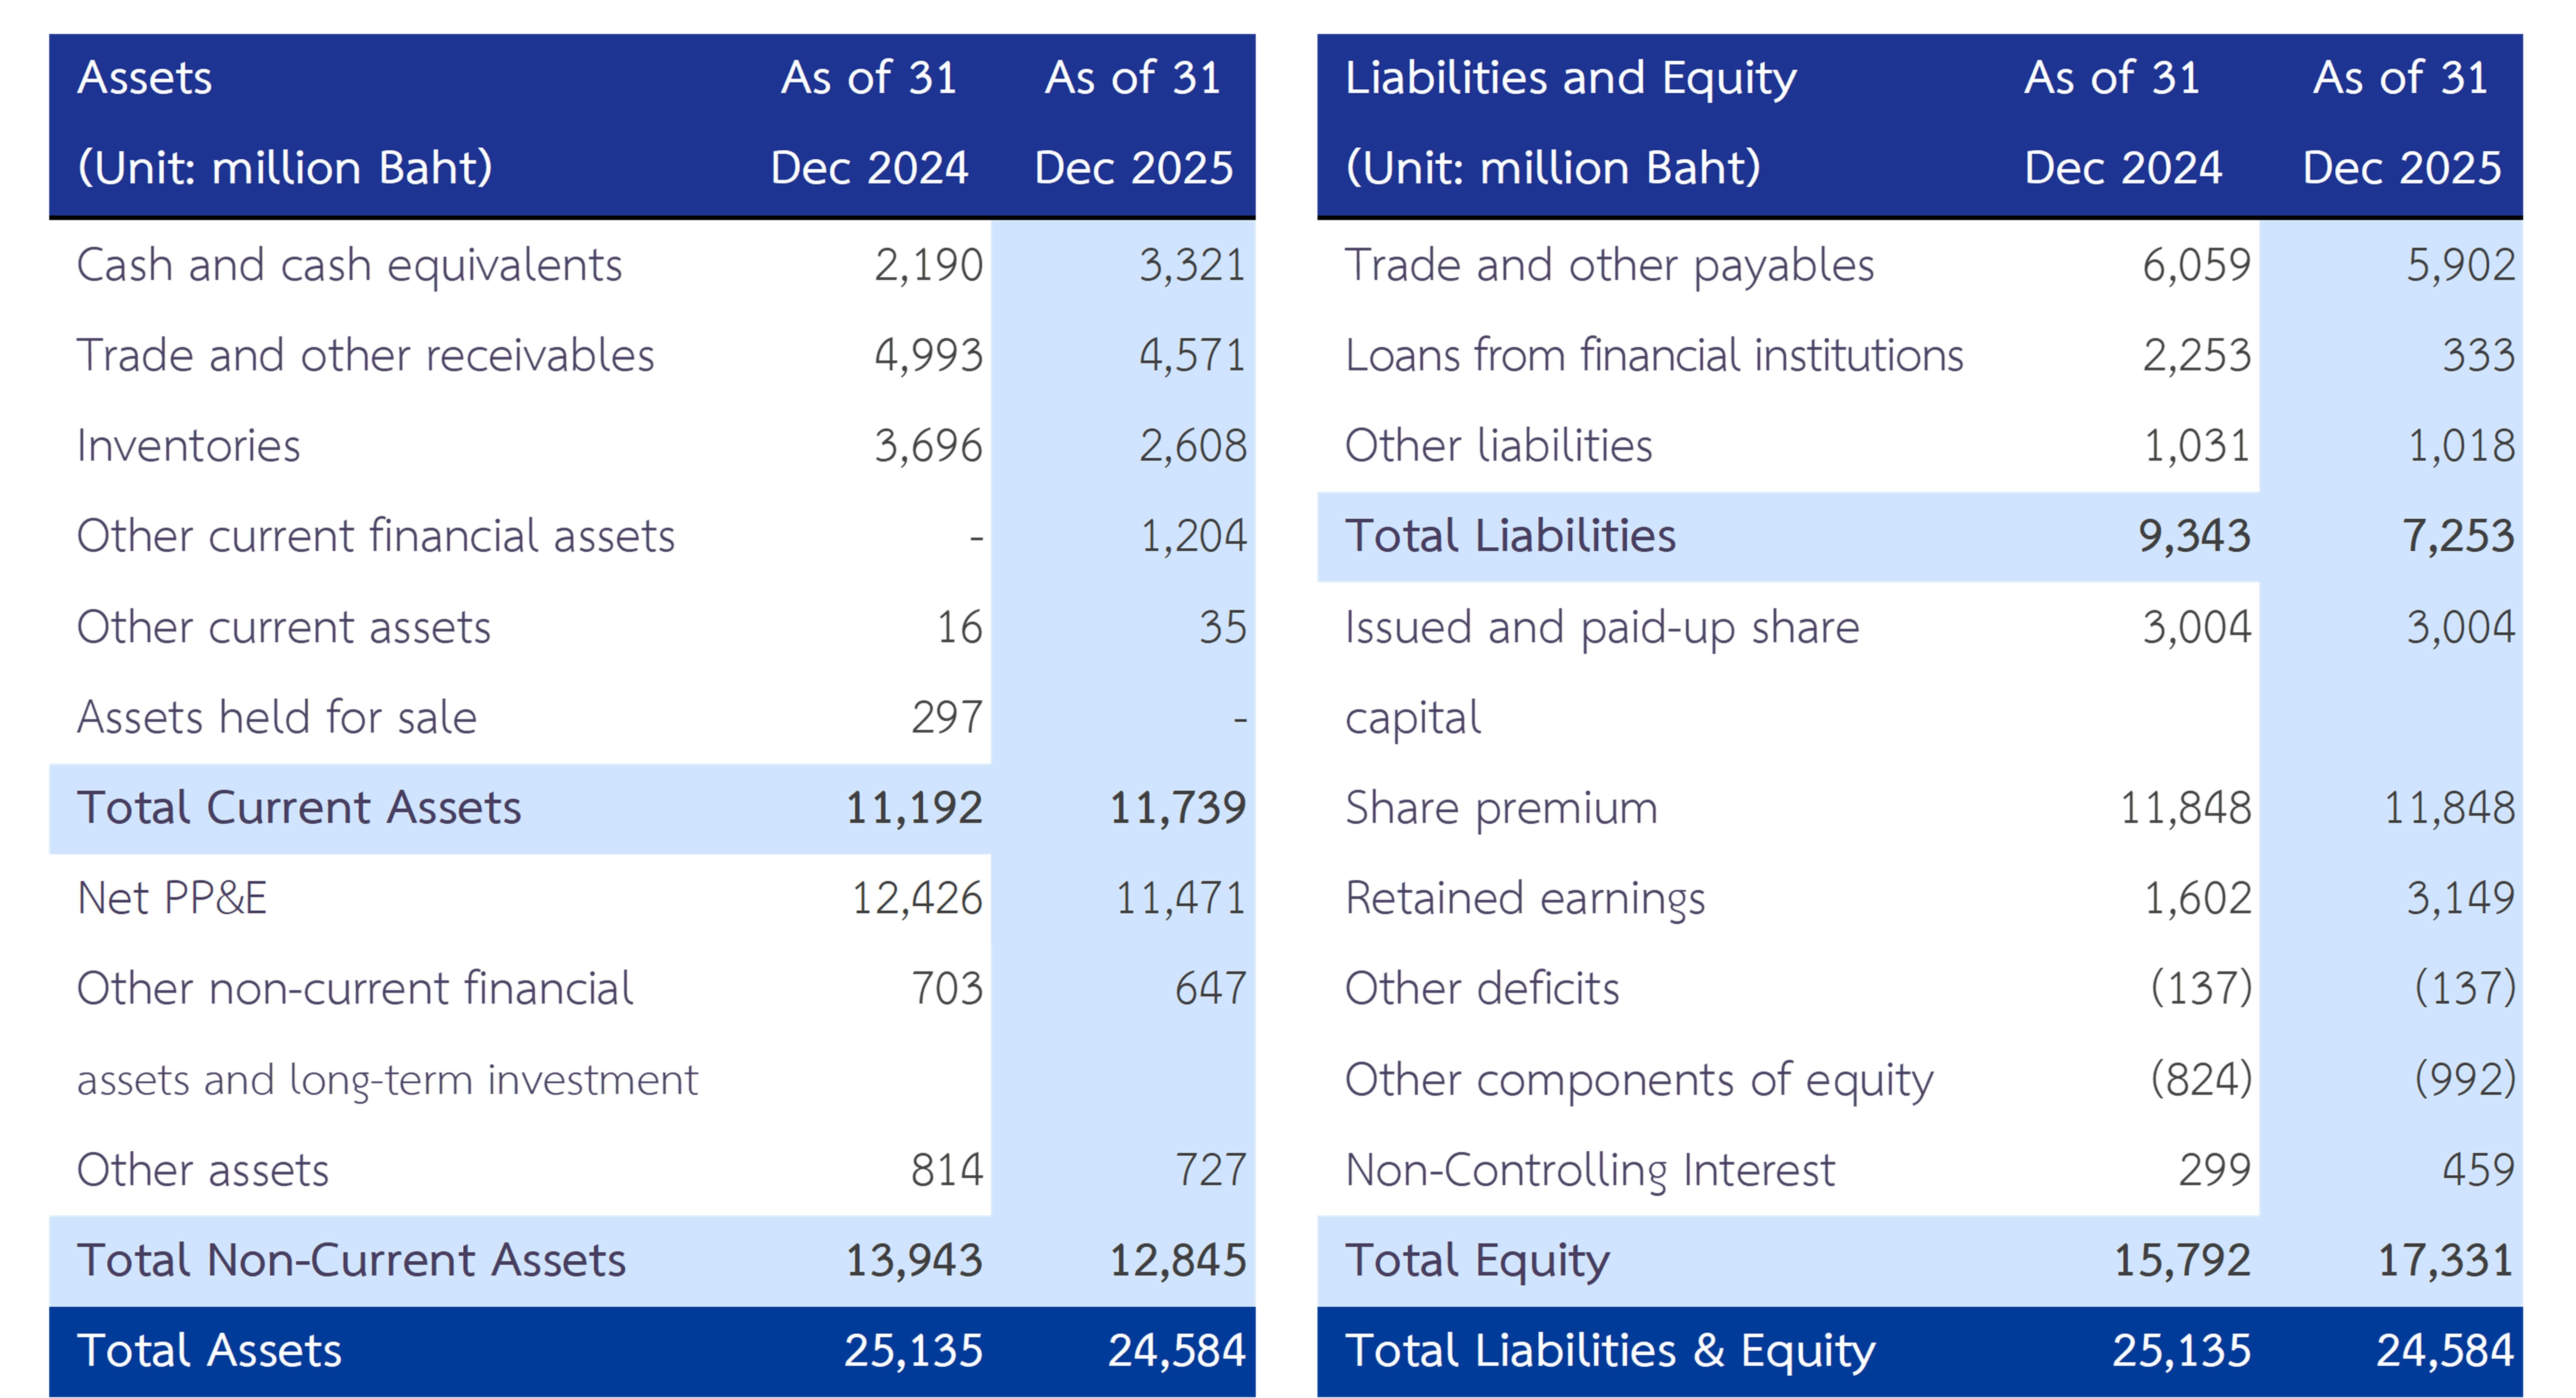
The Company maintains a strong financial position, with improved working capital driven by efficient receivables and inventory management, alongside reduction in interest-bearing debt as planned. This aligns with its strategy to enhance financial stability and support sustainable long-term growth.
As of 31 December 2025, the Company reported total assets of 24,584 million baht, representing a decrease of 2.2% from the previous year. The decline was primarily attributable to reductions in property, plant and equipment, as well as lower inventory levels resulting from effective operational management. This was partially offset by temporary investments in overseas fixed deposits and higher cash generated from operating activities. Total liabilities stood at
7,253 million baht, decreasing by 22.4% year-on-year, mainly due to the repayment of short-term borrowings from financial institutions and a reduction in trade payables. Shareholders’ equity amounted to 17,331 million baht,
an increase of 9.7% compared to the previous year, driven by higher retained earnings in line with improved operating performance, net of dividend payments during the period.
Cash Flow Analysis
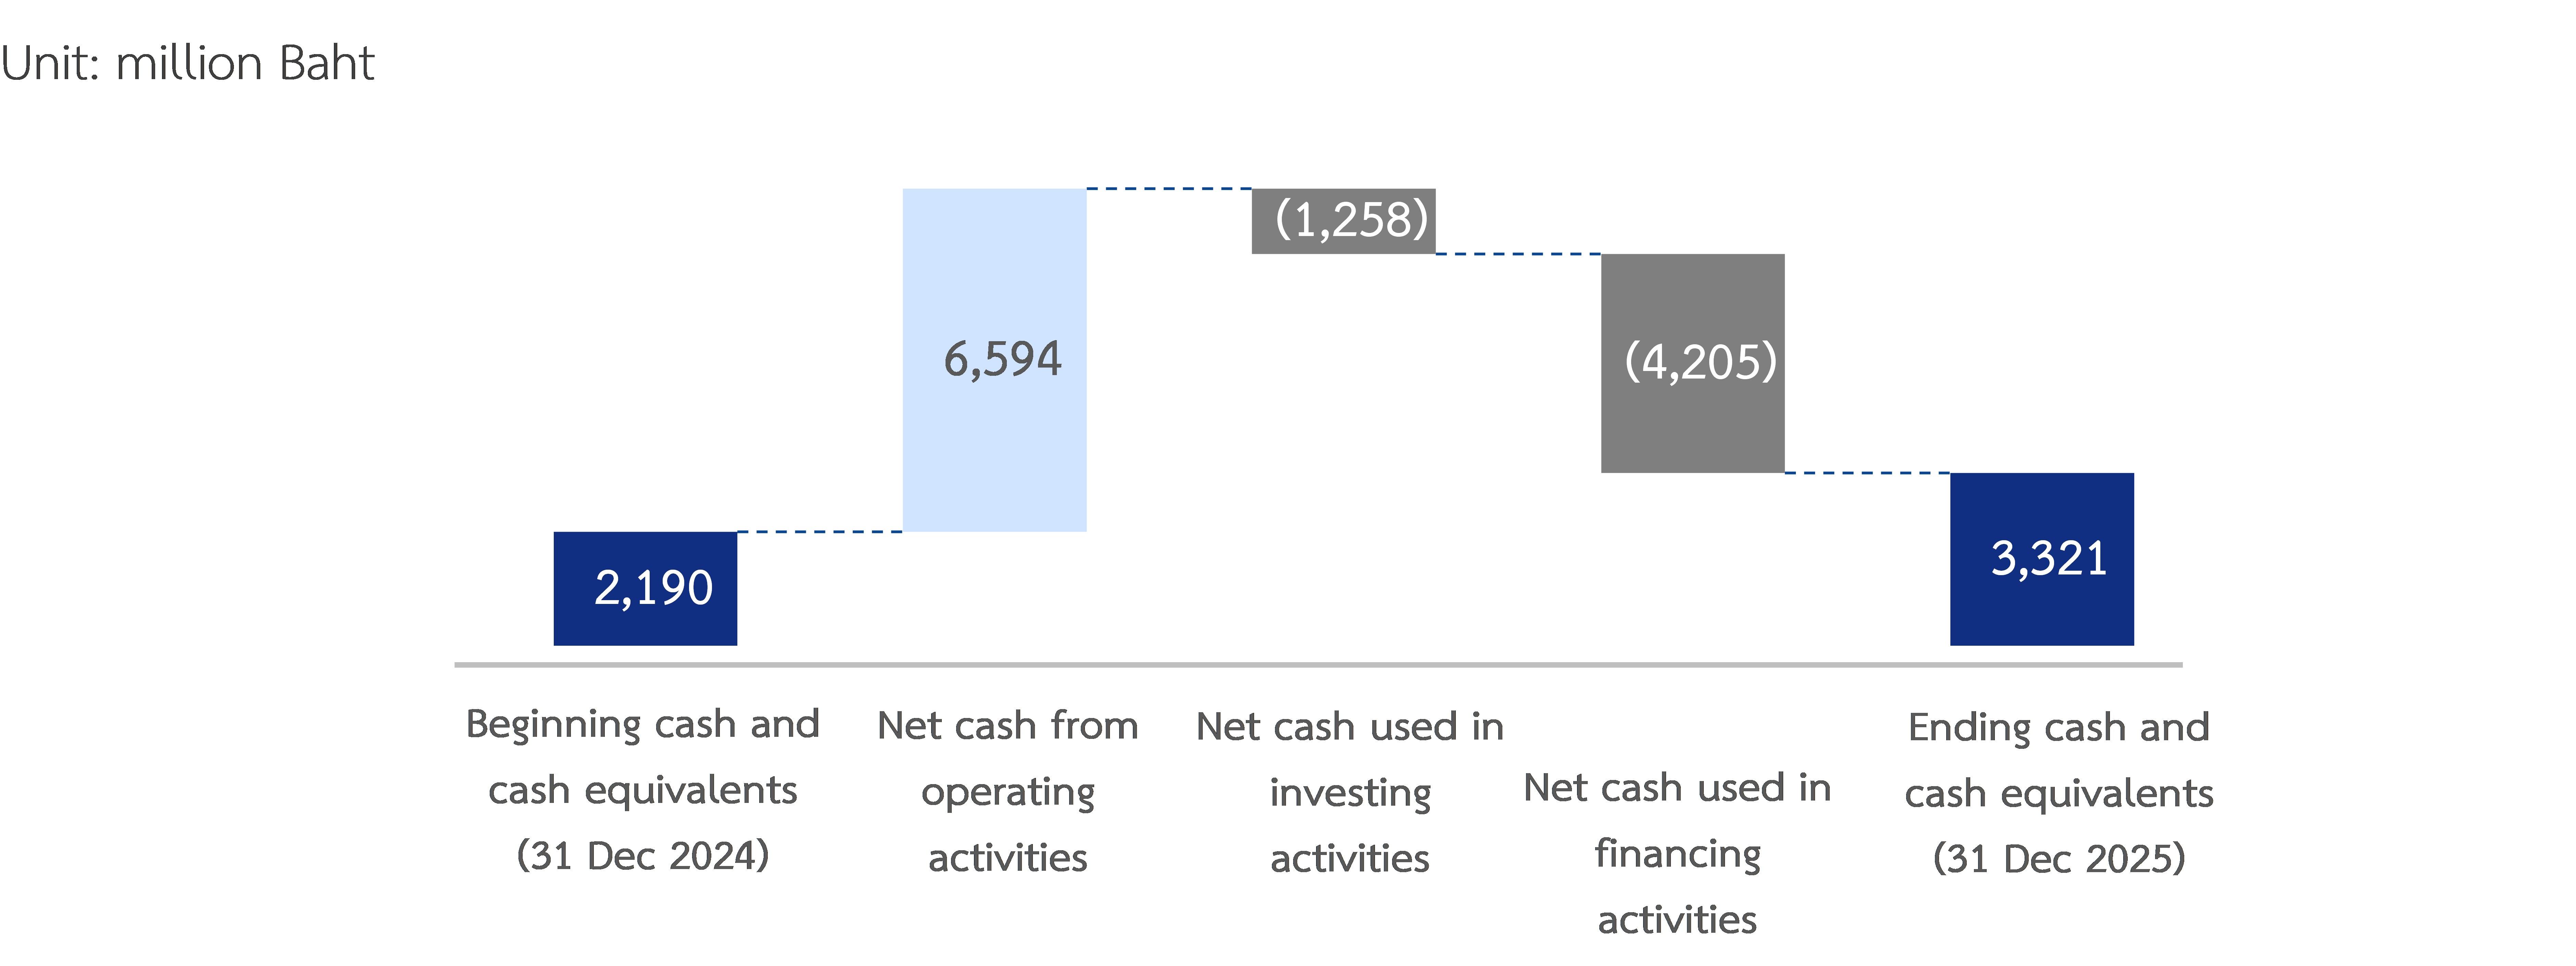
As of 31 December 2025, the Company had cash and cash equivalents of 3,321 million baht, an increase of 1,131 million baht from 31 December 2024. Net cash generated from operating activities amounted to 6,594 million baht. Net cash used in investing activities totaled 1,258 million baht, primarily attributable to the expansion and efficiency enhancement of beverage manufacturing facilities in Thailand and investments in financial assets, partially offset by cash proceeds from the divestment of its investment in the glass bottle manufacturing and distribution business in Myanmar (MGE Group), as well as dividends received from investments in joint ventures. Net cash used in financing activities amounted to 4,205 million baht, mainly from the repayment of short-term borrowings from financial institutions and the payment of dividends for 2024 and interim dividends for the first half of 2025.
Operating Results & Profitability
The gross profit margin for 2025 was 40.1%, representing an increase of 2.8 percentage points from the previous year. This improvement was driven by enhanced production efficiency following the optimization of production capacity allocation, prudent and forward-looking cost management, lower raw material and energy costs, and a higher proportion of revenue generated from international markets.
Liquidity & Capital Adequacy
The Company’s cash conversion cycle was 60 days, a decrease from the previous year. This improvement was primarily driven by an extended average payable period and a shorter average inventory holding period, reflecting effective working capital management and efficient inventory control. The average collection period was 58 days, within the Company’s credit terms of 15 to 100 days, demonstrating close monitoring and prudent management of credit risk. In addition, the Company maintained strong liquidity, with a current ratio of 1.8 times.
Debt Obligations & Off-Balance-Sheet Management
In 2025, the interest-bearing debt-to-equity ratio stood at 0.04 times, while the net interest-bearing debt-to-equity ratio was -0.16 times. These ratios reflect the Company’s strong financial position and readiness to pursue potential investment opportunities.
Material & Related-Party Transactions
For the year ended 31 December 2025, the Company and its subsidiaries did not have any significant transactions. Further details on related-party transactions have been disclosed in Section 9.2.
Other Analysis
| Title | Description |
|---|---|
| Dividend | OSP has a dividend payout policy to shareholders of at least 60% of consolidated net profit after deducting the legal reserve. On 25 February 2026, the Board of Directors passed a resolution to propose to the Annual General Meeting of Shareholders, to be held on 29 April 2026, approval of a total dividend payment of the year 2025 from the operating results from 1 January 2025 to 31 December 2025, and from retained earnings at a rate of 0.80 baht per share, totaling approximately 2,403 million baht or equivalent to dividend payout ratio of 66%. The total dividend includes as follows:
|
| Corporate Sustainability | Following the announcement of its commitment to achieving Carbon Neutrality by 2050, the Company has established a sustainability framework and implement guidelines to steer its operations toward this goal. Progress is regularly monitored and evaluated to ensure alignment with the target. For the first phase of Osotspa’s sustainability implementation (2019–2025), the progress and key achievements can be summarized as follows:
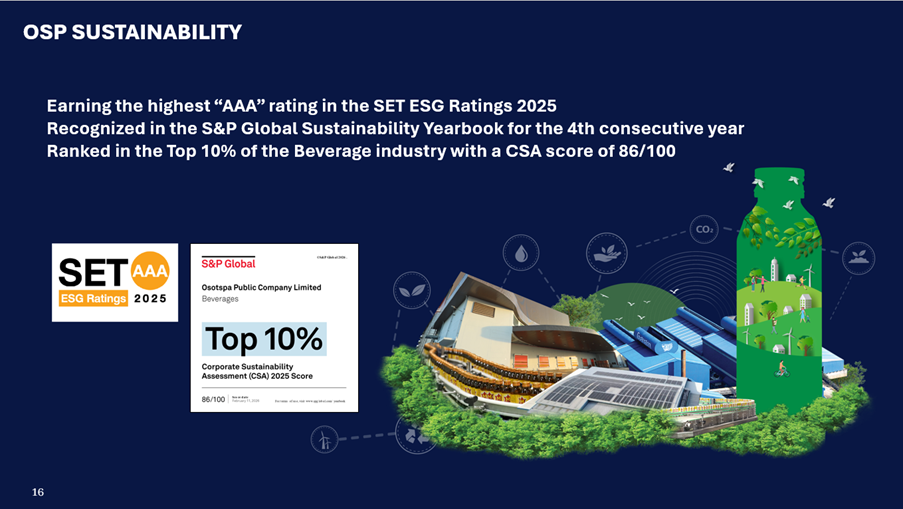
In addition, Osotspa has earned global sustainability acclaim in the beverage industry, recognized by S&P Global Dow Jones Sustainability Indices (DJSI) with the score of 86/100, placing OSP in the Top 10% of companies in the beverage sector. The Company was upgraded to AAA rating in the Agriculture and Food Industry category under the 2025 SET ESG Ratings by SET.
|
Debt Securities with Financial Ratio Requirements
Debt Securities with Financial Ratio Requirements Issued?
No
Factors That May Affect Financial Condition
Factors or Incidents That May Materially Affect Financial Condition
In 2026, Osotspa aims to achieve strategic growth in both revenue and profitability (Grow Both Top & Bottom Line).
The Company targets mid-single-digit revenue growth alongside margin improvement through channel optimization, accelerated product innovation, and international expansion.
Revenue growth in 2026 will be driven by the strategy “Executing Excellence, Empowering the Future,” focusing on strengthening core brands, accelerating innovation, expanding distribution channels, and growing overseas markets.
This will be reinforced by the “ONE OSP” framework, promoting organizational alignment through shared priorities, entrepreneurial decision-making, disciplined execution with a strong sense of ownership, removal of operational constraints, and expansion of core businesses while developing new growth engines.
This strategic direction is supported by strong organizational foundations in talent, digital technology, governance, and compliance, with clear financial targets that include revenue growth, margin enhancement through disciplined SG&A control and effective cost management, as well as a capital expenditure (CAPEX) plan of approximately 400–500 million baht to support innovation, digital technology, and sustainable distribution systems.
Regarding financial reporting, Thai Accounting Standard No. 21 (TAS 21) on The Effects of Changes in Foreign Exchange Rates will become effective for accounting periods beginning on or after 1 January 2026. The revised standard introduces updated guidance on assessing currency exchangeability and determining exchange rates when currencies are not exchangeable, resulting in the withdrawal of certain existing standards. Currently, the Group translates foreign currency transactions using exchange rates announced by the Bank of Thailand. Upon adoption of the revised standard, the Group expects significant impacts on its consolidated statement of financial position as of 1 January 2026, including a decrease in retained earnings of 266 million baht, a decrease in other components of equity of 1,169 million baht,
a decrease in non-controlling interests of 163 million baht, a reduction in total assets of 2,118 million baht, and
a reduction in total liabilities of 521 million baht.